
Beacon Knowledge Centre by TWMC
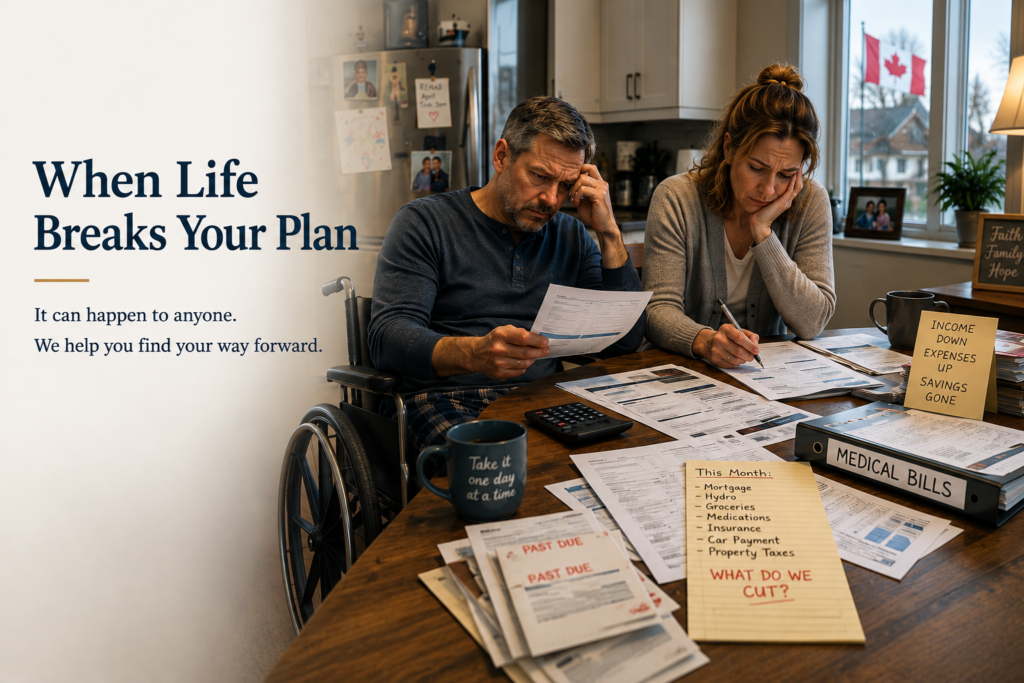
Life rarely follows a straight line. When circumstances change unexpectedly, a good plan gives us something to navigate by.
By David B. Stiglick, BA — Founder, TWMC – The Wealth Management Centre
Somewhere underneath every financial plan sits an assumption: that tomorrow will look at least somewhat like today. Then life changes. A diagnosis arrives. A relationship ends. A job disappears. A business changes direction. Retirement comes earlier than expected. A loved one dies. Suddenly, decisions that once seemed straightforward can look very different.
The plan has not necessarily failed. Life has changed — and the plan needs to change with it.
That distinction matters. Good planning is not about predicting every storm that may come our way. It is about creating enough understanding, flexibility and resilience that when circumstances change, we can reassess where we are, determine what matters most, and begin finding our way forward.
When the Plan Changes
When life disrupts a financial plan, our first instinct may be to solve everything at once. We want to protect every goal, preserve every deadline and somehow put the original plan back together. But during a major transition, trying to solve everything immediately can make an already difficult situation feel even more overwhelming.
A better starting point is to recognize that the plan may need to change because life has changed. Some decisions will require immediate attention. Others can wait. Some goals may remain exactly the same but require a different timeline or strategy. And occasionally, a goal itself may need to be reconsidered.
One useful way to navigate that process is to think about three simple waypoints: Chart the Essentials. Weather the Loss. Reset the Course.
Chart the Essentials
When the plan breaks, the first priority is not to rebuild the entire future. It is to understand what requires attention now. Which expenses must be covered? Which financial commitments cannot wait? What income and resources are available? Which decisions are reversible, and which could have lasting consequences?
Longer-term goals do not necessarily disappear. Retirement, education, home ownership, business plans or estate goals can remain on the chart. But during a major transition, the immediate task is to stabilize the present before trying to redesign the future.
Weather the Loss
Financial transitions are rarely only about money. A job loss is more than a change in income. A separation or divorce is more than a division of assets. An illness or disability can affect much more than a financial projection. The death of someone we love can change responsibilities, relationships, priorities and the future we thought we were building together.
In moments like these, there can be a natural temptation to move immediately into problem-solving mode. Budgets need attention. Forms need to be completed. Accounts may need to change. Decisions have to be made. Those practical matters are important, but so is recognizing the human side of what has happened.
Sometimes we need time to acknowledge the future we expected before we can clearly begin planning for the future that now lies ahead. That is not a failure of planning. It is part of navigating a significant life transition.
Reset the Course
Sometimes resetting the course means changing a timeline. Retirement may come later—or earlier—than expected. A home purchase may need to wait. Education plans may need to be adjusted. A business may take a different direction. The destination may still matter, even though the route has changed.
At other times, the transition changes the destination itself. Priorities evolve. Responsibilities change. What seemed important five years ago may no longer reflect the life we are living today. Good planning allows us to reconsider those assumptions rather than remaining tied to a plan that no longer fits.
The old plan was not necessarily a failure. It reflected the information, circumstances and priorities that existed at the time. When those circumstances change, the goal is not to force life back into the old plan. It is to build a new plan around the life that exists now.
Planning for a Life That Changes
No financial plan can anticipate every diagnosis, career change, family transition, economic disruption or personal loss. Nor should we expect it to. The value of planning is not that it predicts everything that will happen. Its value is that it gives us a framework for making better decisions when the unexpected happens.
That means periodically revisiting the facts of our lives, our goals, our responsibilities, our resources and the risks we face. When something significant changes, the plan deserves another look—not because something went wrong, but because the information on which our decisions are based has changed.
A Steady Point of Reference
When life becomes uncertain, we do not always need to know exactly where the journey will end. Sometimes we simply need a steady point of reference—something that helps us understand where we are, what matters most right now, and what the next reasonable step might be.
That is one of the most useful roles a financial plan can play during life’s transitions. It cannot prevent the storm, and it cannot remove the human difficulty that comes with it. But it can help bring structure to uncertainty, identify the decisions that matter most, and provide a framework for moving forward.
A lighthouse does not stop the storm. It helps us find our way through it.
When Life Changes, Revisit the Plan
If you are experiencing a significant life transition, you do not need to have every answer before beginning to reconsider your financial plan. In many cases, the transition itself is the reason to review it.
Start with what has changed. Identify what needs attention now. Give yourself permission to reconsider assumptions that may no longer fit. Then, when you are ready, begin charting the next course.
Life’s transitions may change our direction, but they do not have to determine our destination.
Educational Information
This article is provided for general educational and informational purposes only and should not be considered individualized financial, investment, insurance, tax, legal or accounting advice. Individual circumstances vary. Where appropriate, readers should consult qualified professionals regarding their specific circumstances.
Last reviewed: August 2026
E&OE