
Helping Aging Parents Financially: A Guide for the Sandwich Generation
By David B. Stiglick, BA — Founder, TWMC – The Wealth Management Centre
There is a moment many families recognize only in hindsight. A parent mentions a bill they forgot to pay. Mail begins accumulating. Money conversations that once seemed routine become more difficult.
Helping aging parents can involve much more than providing financial support. It may mean understanding their wishes, organizing information, preparing for future decisions and considering how assistance could affect everyone involved.
Start With a Conversation, Not a Takeover
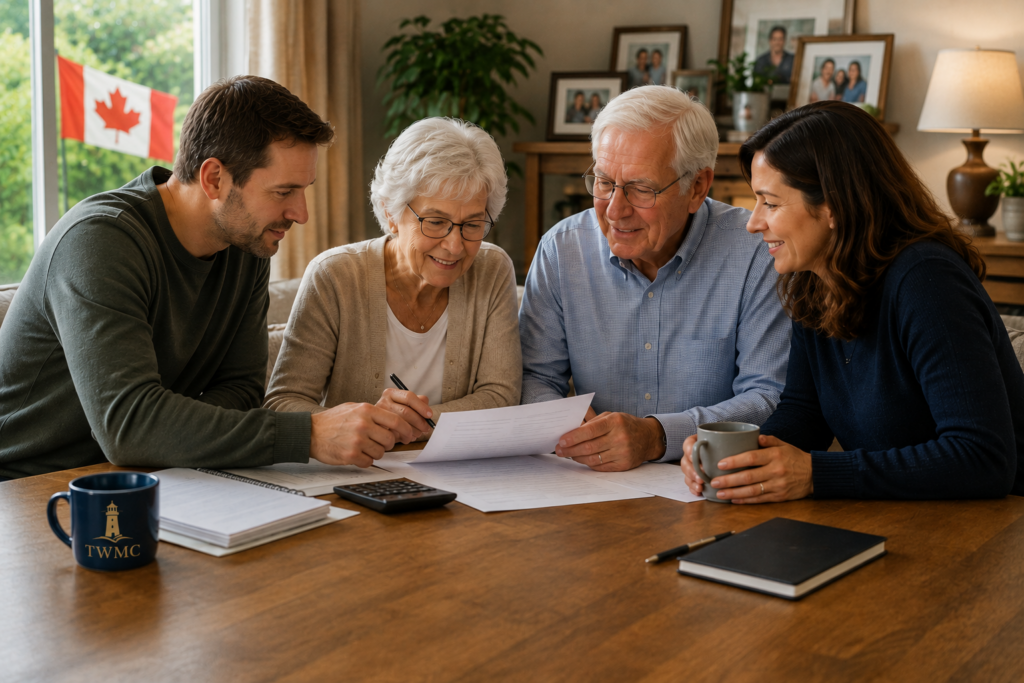
The starting point does not have to be a spreadsheet. It can simply be a conversation.
Ask your parents what kind of help they would be comfortable receiving, where they hope to live as they age and how involved they would like family members to be in financial matters.
The objective is not to take control. It is to understand preferences while your parents are able to express them and to identify decisions that may be easier to address before circumstances become urgent.
Where siblings or other family members are involved, discussing responsibilities early can also help establish clearer expectations.
Build a Clear Picture of Their Finances
With your parent’s permission, it may be helpful to understand the major pieces of their financial situation, including:
- income sources such as CPP, OAS, pensions and investments
- regular expenses
- debts and other financial obligations
- insurance coverage
- important financial and legal documents
- the professionals they currently work with
The purpose is not to pry into someone’s finances. It is to help the family understand what resources, responsibilities and decisions may be involved.
Different families will face very different circumstances. Some parents may need occasional help organizing bills. Others may eventually consider changes in housing, transportation or care arrangements.
Get the Legal Pieces in Order
Legal authority deserves particular attention.
In Ontario, a Continuing Power of Attorney for Property can authorize a trusted person to make financial decisions on another person’s behalf and can continue if the person later becomes mentally incapable. Family members, including spouses and adult children, do not automatically receive authority to manage another adult’s financial affairs.
Because Powers of Attorney create significant legal responsibilities, families should obtain appropriate legal advice when preparing or reviewing these documents.
It can also be useful to keep important information—such as account details, insurance policies, wills and professional contact information—organized securely and accessible to the appropriate authorized people.
Helping Without Losing Sight of Your Own Plan
Families support aging parents in many different ways. Assistance might involve transportation, household expenses, care costs, housing decisions or simply helping organize financial information.
Before committing to ongoing financial support, it is worth considering how that assistance fits within your own household cash flow, retirement planning and other financial responsibilities.
The objective is sustainable help—not creating a second financial problem while trying to solve the first one.
Keeping clear records of financial assistance, loans, gifts or shared expenses may also reduce confusion among family members later.
What About Home Equity?
Some older homeowners consider accessing home equity, including through a reverse mortgage.
A reverse mortgage can provide access to part of a home’s equity without immediately selling the property, but interest accumulates and other costs may apply. Over time, the amount owed can increase and the remaining equity available to the homeowner or estate can decline.
For that reason, home-equity decisions deserve careful comparison with other options and, where appropriate, independent financial and legal advice.
Support Available to Canadian Caregivers
Some Canadian caregivers may qualify for the Canada Caregiver Credit.
Eligibility and the amount that may be claimed depend on factors including the family relationship, the dependant’s circumstances and net income, and other credits being claimed.
Depending on the circumstances, eligible medical expenses paid for a dependant may also be relevant for income-tax purposes.
Tax rules and personal circumstances differ, so eligibility should be confirmed using current CRA information or with an appropriately qualified tax professional.
Watch for Changes That Deserve Attention
Changes such as unpaid bills, unusual banking activity, unfamiliar purchases, unexplained financial changes or sudden changes to legal documents can be reasons to ask questions.
They do not, by themselves, establish that someone has lost mental capacity or is experiencing financial abuse.
However, financial exploitation of older adults is a genuine concern. Financial abuse can include unauthorized use of money or property, pressure involving financial decisions and misuse of a Power of Attorney.
The appropriate response is careful attention, respectful conversation and, when necessary, assistance from the appropriate legal, financial, health or community professionals.
The Bottom Line
Helping aging parents financially works best when families have time to think rather than being forced to react to a crisis.
Starting conversations earlier, organizing information, understanding available resources and obtaining appropriate professional guidance can make difficult decisions easier to navigate.
And just as importantly, caregiving decisions should be considered within the broader financial circumstances of everyone involved.
That is what financial planning through life’s transitions is really about—not simply numbers, but understanding how changing circumstances affect the decisions families have to make.
The Beacon Question™
Has anything changed in your family’s life that may deserve a financial planning conversation?
This material is provided for general educational and informational purposes only. It is not intended to provide individualized financial, investment, insurance, legal, tax, accounting or other professional advice, and it does not constitute a recommendation or endorsement of any particular financial product, strategy or service. Individual circumstances vary. Where appropriate, readers should consult qualified financial, legal, tax, accounting or other professionals regarding their particular situation.
Last reviewed: August 8, 2026
Errors and Omissions Excepted (E&OE)